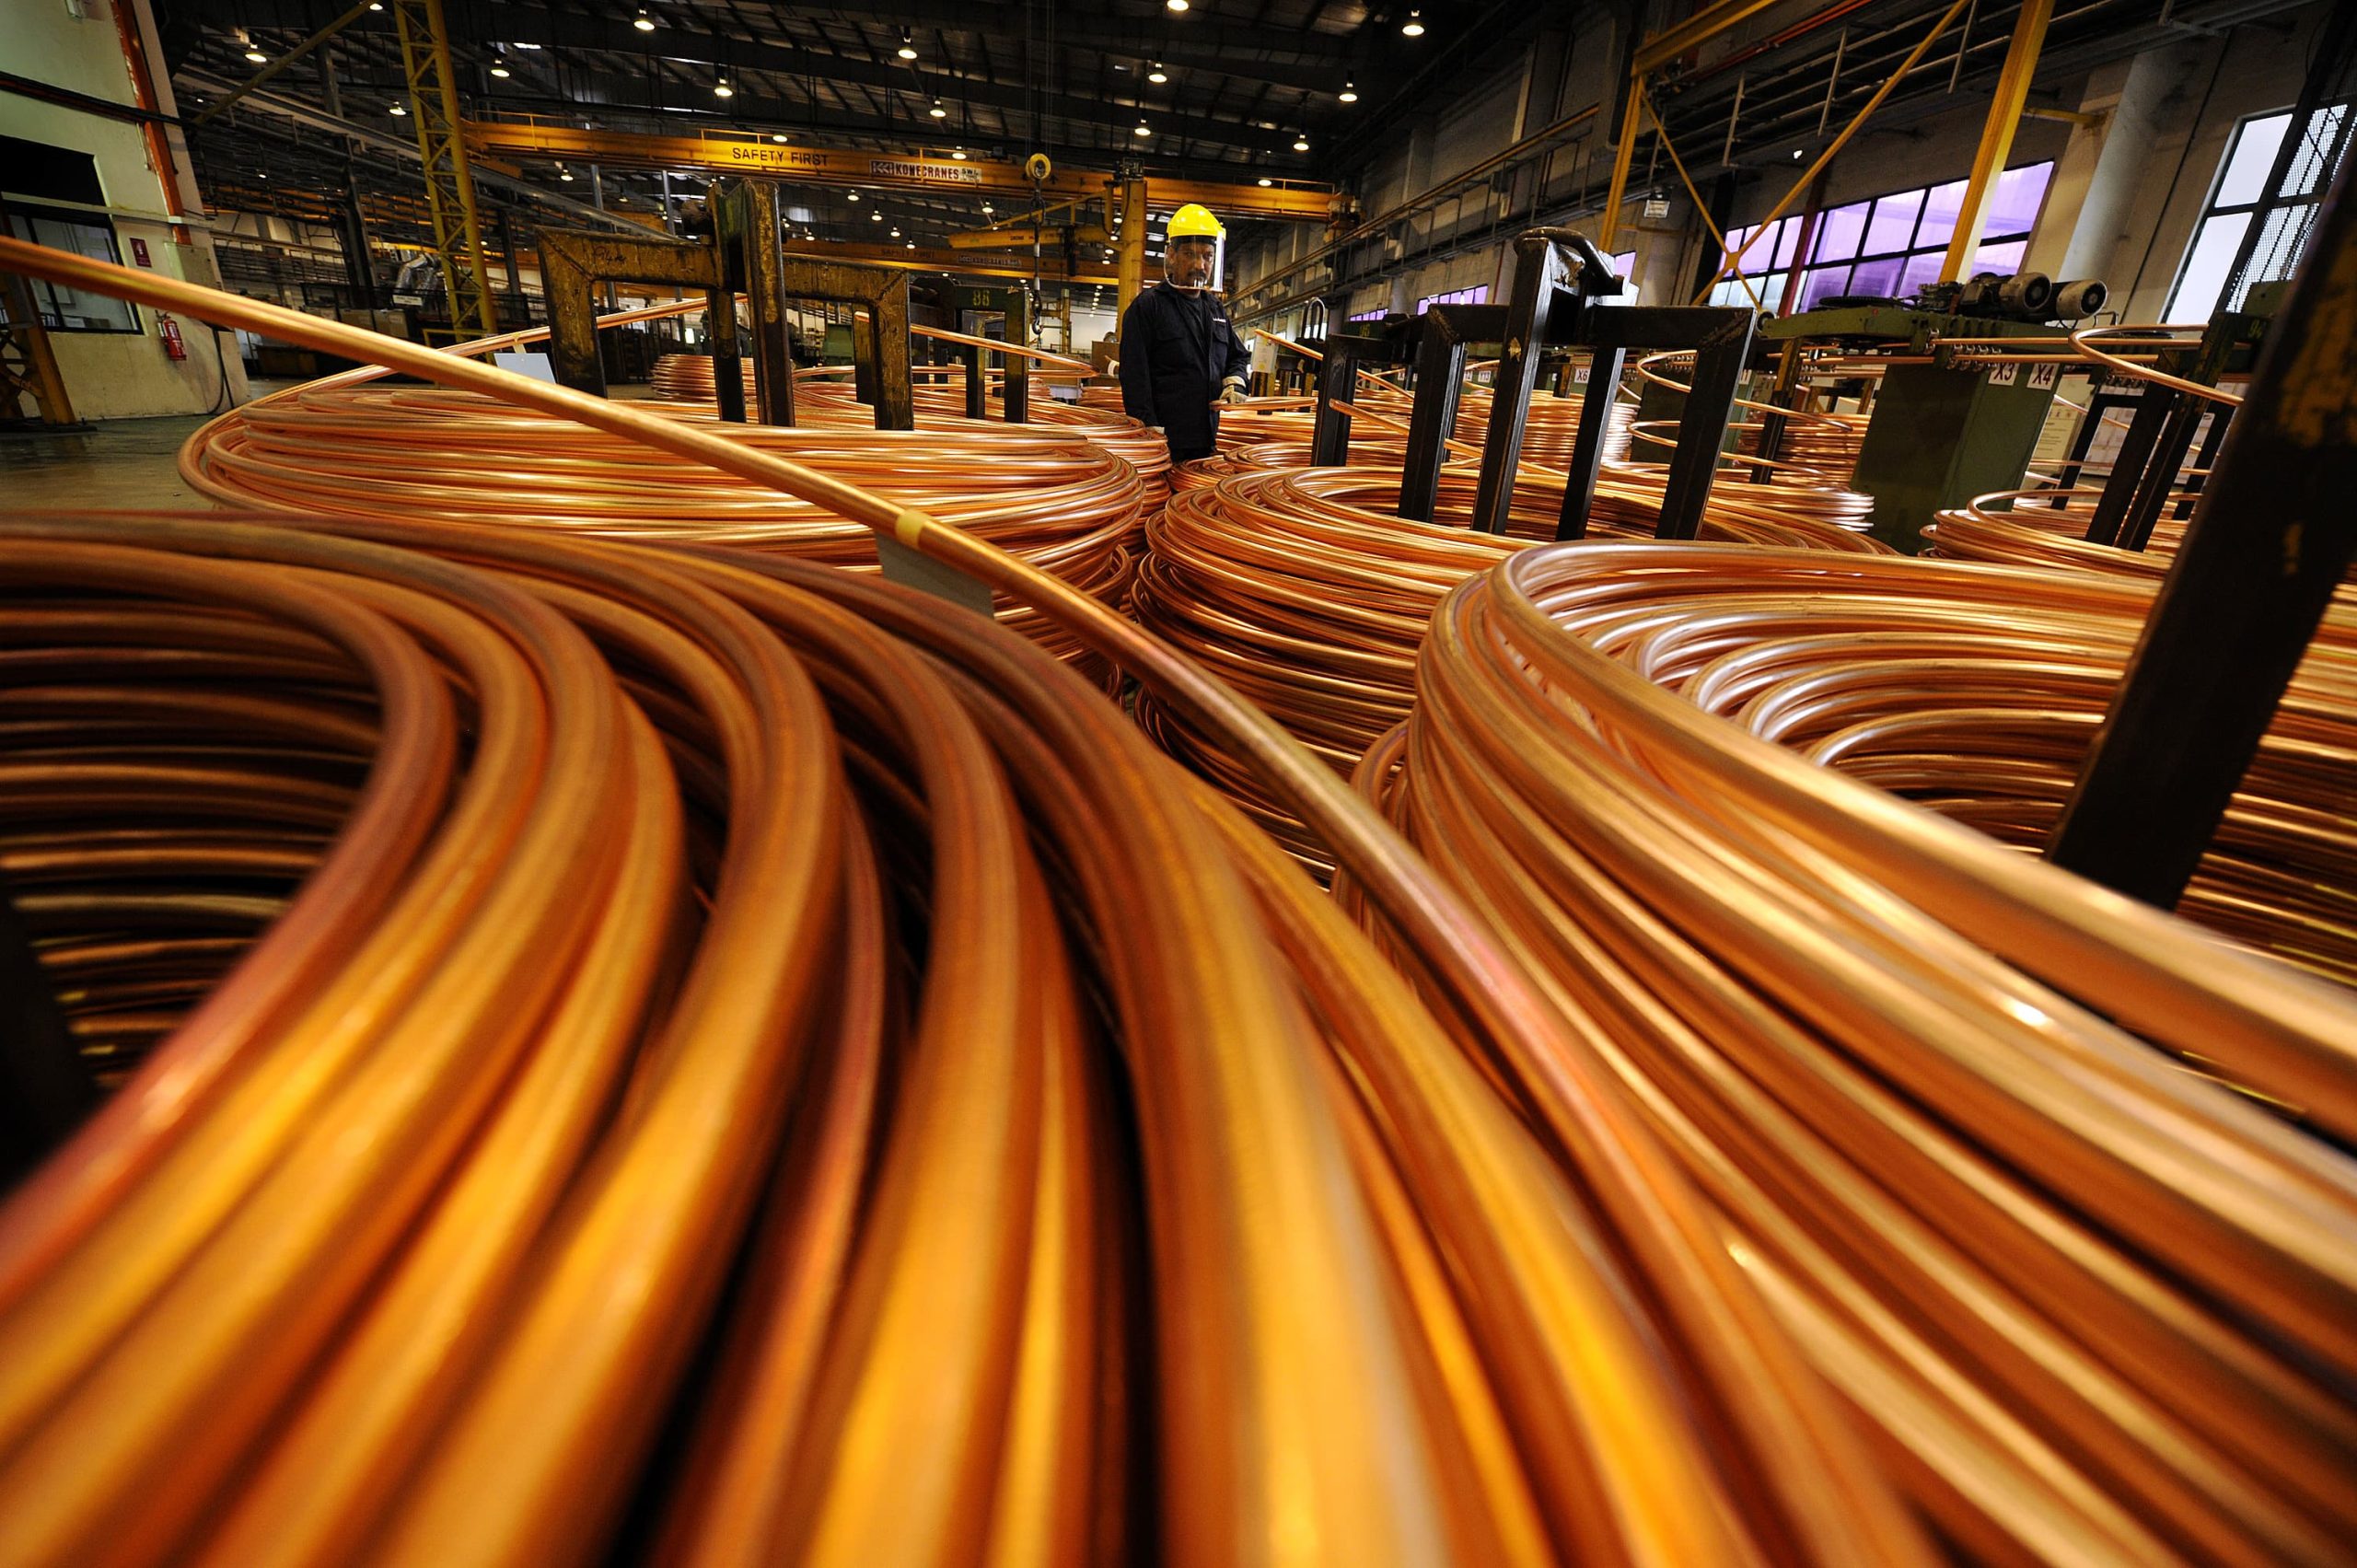
The intricate dance between copper prices on two continents has transformed into a daily read on Washington’s tariff intentions. The industrial metal, vital for construction, electronics and transportation, has been climbing for over a year, with futures touching a record high of nearly $6.90 per pound last week.
For years, the spread between U.S. COMEX futures and London Metal Exchange prices served as a workhorse for physical traders, banks, hedge funds, producers and consumers. They used it to profit from temporary price differences and to hedge against price risk between the two markets. Historically, the arbitrage was driven by factors such as Chinese demand shocks or supply disruptions in South America.
Now, according to analysts at Societe Generale, the trade has been upended by the prospect of fresh Section 232 tariffs on refined copper, pending a White House investigation. Investors are increasingly using the COMEX premium as a gauge of further duties, watching every tick for clues about policy decisions.
The U.S. already charges a 50% levy on imports of semi-finished copper products and certain other products made with copper. The Commerce Department has recommended a phased universal tariff of 15% on refined copper from Jan. 1, 2027, rising to 30% on Jan. 1, 2028.
“The COMEX-LME spread has increasingly become a gauge of U.S. tariff expectations, with a wider premium signaling greater perceived tariff risk and continuing to pull metal into the U.S.,” Ewa Manthey, commodities strategist at ING, told CNBC via email.
The pull of that premium is evident in trade flows. The U.S. imported more than 200,000 metric tons of copper in July, its highest level in 12 years.
Societe Generale analysts, led by Mike Haigh, head of FIC and commodity research, said U.S. policymakers have become increasingly concerned about the country’s reliance on imported refined copper as AI infrastructure, grid modernization and defense spending turbo-charge global demand. The Section 232 probe reflects a broader objective in “securing access to a material seen as critical to both economic growth and national security,” he said.
To translate the spread into tariff odds, SocGen modelled the cost of moving LME-grade copper from European warehouses to the U.S. East Coast, and compared that all-in delivered price with COMEX futures. The current COMEX premium over fully delivered LME metal implies a 14.6% likelihood of the Commerce Secretary’s recommended phased universal tariff of 15% by January 2027. That rises to a 37% probability of a 30% duty by January 2028.
Natalie Scott-Gray, senior metals demand strategist at StoneX, said the overdue U.S. Section 232 decision on refined copper is now the “single biggest catalyst” facing the copper market. In a recent market commentary, she said comprehensive tariffs would squeeze supply outside the U.S., while no tariffs would unwind the COMEX-LME arbitrage.
Manthey said a wider premium remains supportive for copper prices near term, “particularly as mine supply remains tight and competition for available metal between the U.S. and China intensifies.” She added: “We remain constructive on copper, although tariff uncertainty means volatility is likely to stay elevated.”
As the White House weighs its Section 232 decision, the copper market remains in a state of heightened anticipation. The spread between COMEX and LME prices is likely to keep reflecting policy expectations, while supply tightness and geopolitical competition continue to underpin prices. For now, investors are bracing for volatility as they monitor every signal from Washington.